
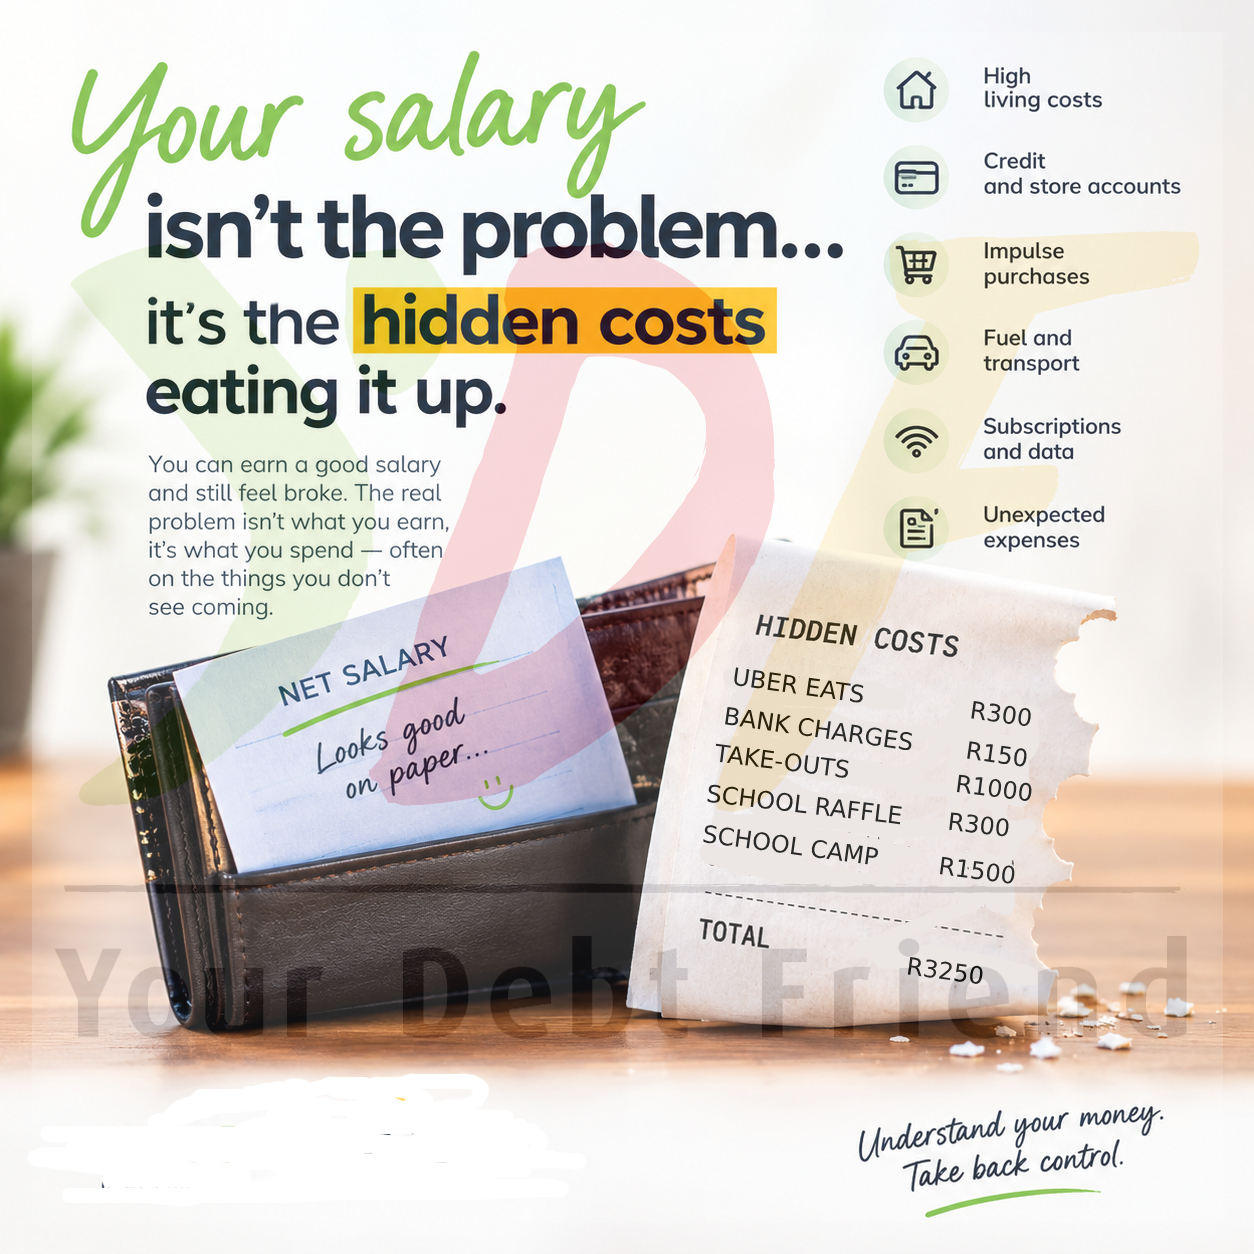

Your salary isn't the
problem: the hidden cost of keeping up
By Zuhair Lewis
Payday comes. So where does your money go?
Your salary lands in your account and,
for a moment, the world is your oyster and everything feels possible.
You can catch up on bills, buy
groceries, fill up your tank and maybe even treat yourself to something
worthwhile. Then the debit orders start rolling in. Your rent is due. Your
insurance comes off. Your credit repayments need attention. Suddenly your bank
balance looks nothing like it did a few days ago.
Sound familiar?
For many South Africans, and people across the world, managing money isn't simply about how much they earn. It's also about how much of their income is already committed before the month even begins.
Pg1
pg2
That's R8 500 already allocated,
leaving just R3 500 for groceries, electricity, toiletries, unexpected expenses
and everything else. And this is before adding any expenses that weren't in the
original plan.
The lesson? A salary can look
substantial on paper and still leave very little room to manoeuvre once your
commitments have been covered. Understanding the difference between your income
and the money you actually have left is an important first step towards making
more informed financial decisions.
Small monthly payments can become a big commitment
In this economy, it's easy to
underestimate an expense when it looks manageable on its own.
A streaming subscription here. A phone
contract there. A clothing account, a credit card repayment and a few purchases
made through a buy-now-pay-later service. By themselves, each payment might
seem affordable. Collectively, they can take up a significant portion of your
monthly income, especially when they all fall within the same period.
That doesn't mean every subscription
or credit purchase is irresponsible. The important question is whether your
total financial commitments remain manageable alongside your essential living
expenses.
Try reviewing your bank statements and
listing your recurring payments. Check which services you still use, whether
any charges are unfamiliar, how much you commit to repayments every month, and
whether there are cheaper alternatives to your subscriptions. You may discover
opportunities to reduce unnecessary costs.
If most of your expenses are essential, however, cutting small luxuries alone may not be enough to resolve the problem.
Pg2
pg3
When debt
repayments start competing with essentials
Debt becomes particularly concerning
when making repayments leaves you without enough money for necessities.
Perhaps you're paying one debt with
another. Maybe you're borrowing money for groceries before payday, or regularly
choosing which account to pay because there isn't enough for everything. These
patterns deserve attention.
Interest and fees can also affect how quickly a balance grows and how much you can realistically repay. In that situation, the solution may require more than spending less on entertainment or takeaways.
It's important to understand your full
financial position, including your income, essential expenses, outstanding
balances and repayment obligations. Recognising the problem early gives you
time to explore your options before the pressure becomes harder to manage.
The pressure to keep up can make things harder
Money decisions don't happen in a
vacuum. Social plans, family responsibilities, online shopping and the pressure
to maintain a particular lifestyle can all influence how we spend. Social media
makes it especially easy to compare your everyday circumstances with someone
else's carefully selected highlights.
Sometimes spending is also connected
to emotional needs: wanting to feel included, rewarding yourself after a
difficult week, or buying something because it offers temporary relief.
There's nothing inherently wrong with
enjoying your money. Financial wellness isn't about removing every pleasure
from your life. It's about understanding your priorities and making decisions
that support both your present needs and your longer-term financial wellbeing.
If your current lifestyle is consistently costing more than your income can support, it may be time to reassess what is realistic for your circumstances. That conversation should begin with understanding, not shame.
Pg3
pg4
How to start taking control of your money
You don't need to overhaul your entire
financial life in one afternoon. Start by getting a clearer picture of what is
happening.
Step 1: Calculate your take-home
income. Start with the amount you actually receive
after deductions, rather than your gross salary.
Step 2: List your financial
commitments. Include housing, transport, utilities,
insurance, debt repayments, subscriptions and other regular expenses.
Step 3: Account for essential
living costs. Groceries, toiletries, medical
expenses and other necessities need to be included. A budget that ignores these
costs won't accurately reflect your financial position.
Step 4: Compare your plan with your
actual spending. Review your bank statements to see
whether your money is going where you expected. Look for recurring expenses,
unplanned purchases and costs you may have underestimated.
Step 5: Identify the real problem. If unnecessary spending is adding to the pressure, consider what you can realistically reduce. If your essential expenses already consume most of your income, or your debt repayments are no longer affordable, a few cancelled subscriptions may not solve the underlying issue.
Step 6: Seek guidance if you need
it. You don't have to understand every financial
product or debt-relief option on your own. If you're struggling with debt,
consider speaking to a registered debt counsellor to understand your
circumstances and the options available to you.
When is it time to consider debt counselling?
Budgeting can help you understand your
money, but it can't always resolve a situation where your debt obligations are
no longer affordable.
Debt counselling is a formal process in South Africa intended to assist qualifying over-indebted consumers. A registered debt counsellor assesses your financial circumstances and explains whether debt review may be suitable. Where appropriate, the process can involve proposing a restructured repayment plan and negotiating with credit providers through the relevant legal process.
Pg4
pg5
When debt
repayments start competing with essentials
Debt becomes particularly concerning
when making repayments leaves you without enough money for necessities.
Perhaps you're paying one debt with
another. Maybe you're borrowing money for groceries before payday, or regularly
choosing which account to pay because there isn't enough for everything. These
patterns deserve attention.
Interest and fees can also affect how quickly a balance grows and how much you can realistically repay. In that situation, the solution may require more than spending less on entertainment or takeaways.
IDebt review is not suitable for everyone, and it has important implications. It can affect your access to further credit, so make sure you understand the process, costs, obligations and eligibility requirements before deciding to proceed.
If you're considering debt
counselling, seek information from a professional registered with the National
Credit Regulator, and ask how the process would apply to your circumstances.
Your financial situation deserves an informed decision, not a rushed one.
Your money should work for your life
If your salary seems to disappear
every month, it doesn't automatically mean you're bad with money. Your
circumstances may involve rising living costs, existing financial commitments,
debt repayments, or a combination of several factors.
The important thing is to understand
what's happening rather than ignoring the numbers or blaming yourself without
examining the situation. Start by reviewing your income, understanding your
commitments and identifying where the pressure is coming from. If debt has
become difficult to manage, professional guidance may help you understand your
next steps.
At Your Debt Friend, we believe that
understanding money should be accessible, practical and free from unnecessary
judgement. If you're struggling with debt repayments and want to explore your
options, get in touch with us to discuss your circumstances and whether debt
counselling may be appropriate for you.
Because understanding your money is
the first step towards making informed financial decisions.
Pg5